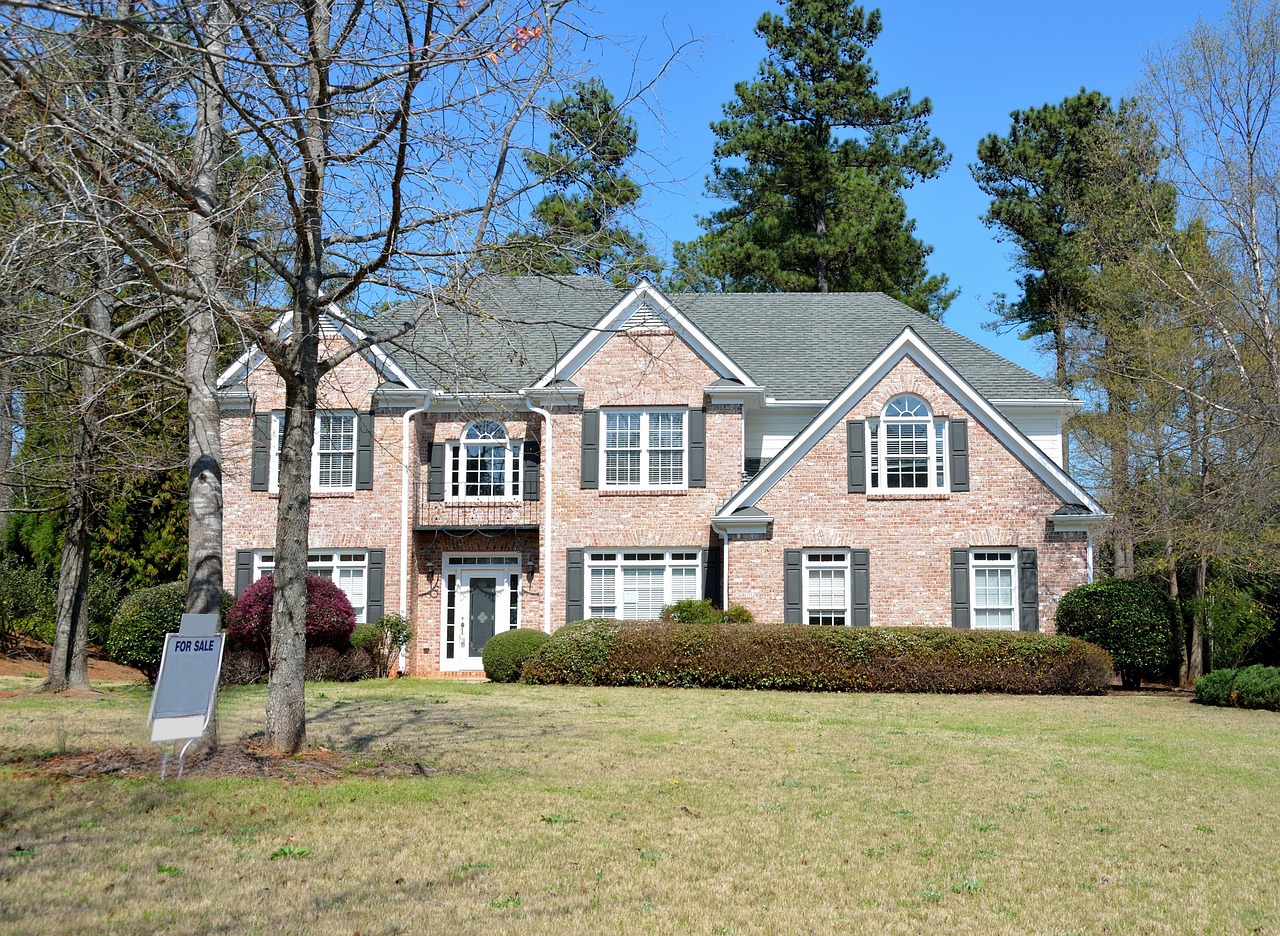
As property values drop, minor home imperfections become major negotiating points, forcing sellers to address perceived renovation costs to secure a sale.
Property market downturn shifts power to buyers
Homeowners are currently navigating a challenging property market, with average values experiencing their most significant annual decline since October 2023. This downturn creates a distinct buyer’s market, granting prospective purchasers greater leverage to negotiate prices.
The average property price across the UK stood at GBP296,285 in October 2026, representing a 0.6% fall compared to September 2026. This environment means that seemingly minor flaws in a home can become major points of contention for buyers seeking to reduce asking prices.
Property value declines and feature deductions
The property market saw an average value fall of 1.2% annually, the steepest decrease recorded since October 2023. This decline, coupled with buyer scrutiny, allows for significant price chipping based on specific home features.
- Converting a bedroom into a dressing room or office could reduce a home’s value by approximately GBP15,000.
- Stripping out original period features might knock up to 10% off a property’s price, equating to GBP27,300 on a typical GBP273,000 home.
- An extension that significantly reduces garden space could diminish a home’s appeal, potentially losing an GBP11,000 premium associated with a decent back garden.
- An old, inefficient conservatory may be viewed as ‘dead space’, potentially reducing the asking price by up to GBP15,000.
- An ancient gas boiler is a major red flag, with buyers potentially chipping GBP5,000 to GBP10,000 off the price for replacement costs.
- Poor kerb appeal, such as an overgrown front garden, could reduce a property’s value by up to 20%, or GBP40,000 on a GBP200,000 home.
- A low Energy Performance Certificate (EPC) rating could cut value by up to 14%, or GBP38,220 on an average GBP273,000 property.
Homeowners face significant financial impact
The current market conditions mean homeowners risk losing tens of thousands of pounds on their property sales due to issues that buyers perceive as future expenses. Andrew Asaam, mortgages director at Lloyds, noted that housing demand is being tested by a challenging economic backdrop.
Buyers are increasingly scrutinising properties, turning what might once have been minor cosmetic issues or personal choices into major deal-breakers. Financial adviser Nouran Moustafa describes this as a ‘mental renovation bill’, where buyers deduct money in their heads before making an offer.
Sellers must anticipate buyer concerns
Homeowners looking to sell now must proactively address issues that contribute to a buyer’s ‘mental renovation bill’ to avoid substantial price reductions. Simple, low-cost improvements can often yield significant returns by making a property more appealing and reducing perceived future spending.
For instance, restoring a converted bedroom to its original function, ensuring a well-maintained boiler, or enhancing kerb appeal can prevent buyers from chipping away at the asking price. The financial outlay for these fixes is typically far less than the potential loss in sale value.
Sellers must confront the ‘mental renovation bill’
Many sellers fail to view their own homes through the critical eyes of a potential buyer. Over-personalisation or neglecting basic maintenance creates an immediate psychological and financial hurdle for purchasers, especially in a market where they have ample choice.
In this buyer-led environment, these perceived costs become powerful negotiation tools. Sellers must therefore invest the time and modest funds required to depersonalise and present a move-in ready home, or be prepared to accept significantly lower offers than they might otherwise achieve.
Future market stability and interest rate shifts
The trajectory of the property market will largely depend on upcoming decisions regarding interest rates and broader economic stability. Any easing of rates could stimulate buyer demand, potentially rebalancing the market dynamics.
- Observe central bank announcements on interest rates for signs of market shifts.
- Monitor inflation figures, as these directly impact both mortgage affordability and renovation costs.
- Watch for changes in consumer confidence, which can influence buyer willingness to enter the market.